Preparation
When the Client Is the Pressure: Navigating Circular 230 Under Real-World Demands
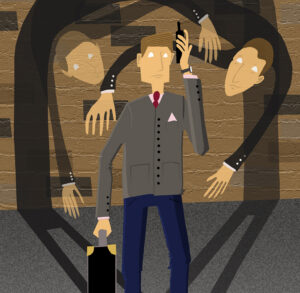 Ethics in tax practice is rarely about not knowing the rule. Most practitioners understand Circular 230. We know the due diligence standards. We know the written advice requirements. We understand the authority thresholds.
The challenge is not technical ignorance.
The challenge is pressure.
Pressure shows up in subtle ways. Urgency. Loyalty. Financial strain. Industry norms. And sometimes, simple insistence. That is where professional judgment is tested.
Circular 230 does not eliminate pressure. It defines how we respond to it.
Due Diligence in Incomplete-Record and Back-Year Engagements
One of the most common ethical stress points arises in back-year cleanup cases. A client walks in with multiple unfiled returns. Documentation is incomplete. Bank statements are missing. Estimates are offered as substitutes for records.
Circular 230 §10.22 requires practitioners to exercise due diligence in preparing returns and determining the correctness of representations made to the Treasury. That obligation does not disappear because the engagement is urgent.
In practice, the tension becomes practical:
- How much reconstruction is reasonable?
- When does estimation become assumption?
- At what point does the file no longer support the position?
The temptation is to resolve the problem quickly. But due diligence is not measured by speed. It is measured by defensibility.
When documentation is weak, the safest answer is often the hardest one: pause the engagement until the file can support the return.
Client Pressure and Aggressive Positions
Client pressure rarely presents itself as misconduct. It often sounds like confidence.
“My last preparer deducted this.”
“Everyone in my industry does it.”
“It’s a gray area.”
Circular 230 requires that positions taken on a return meet the appropriate standard of authority. Whether the threshold is reasonable basis, substantial authority, or disclosure-supported risk, that determination belongs to the practitioner.
It is not a client vote.
Preparer penalties under Internal Revenue Code (IRC) §6694 are not theoretical. They attach to the individual signing the return. The client may request the position. The practitioner owns the
consequence.
The ethical moment is quiet. It is the decision to push back. To explain risk clearly. To decline a position that does not meet the standard. Those decisions shape the profession more than any technical memorandum.
Artificial Intelligence-Generated Research and Emerging Risk
A newer pressure point has emerged. Clients increasingly arrive with artificial intelligence (AI)-generated summaries of tax positions. Some are thoughtful. Some are confidently incorrect. Many lack primary authority citations.
Circular 230 §10.22 still applies. Due diligence requires independent verification. Practitioners must evaluate primary sources, confirm authority, and assess whether the position satisfies the
appropriate standard.
Technology accelerates access to information. It does not transfer liability.
In fact, the risk may increase. Confident language can create the illusion of authority. When clients believe they have already “done the research,” professional skepticism becomes even more
important.
Artificial intelligence can assist in analysis. It cannot replace professional judgment.
Written Advice and Documentation Standards
Written advice carries additional responsibility. Circular 230 §10.37 requires practitioners to base written advice on reasonable factual and legal assumptions, consider all relevant facts, and avoid reliance on unreasonable representations.
In practice, written advice often begins informally. An email response. A quick memo. A summary after a call.
But informal communication can become formal evidence.
Have assumptions been documented? Have risks been clearly explained? Has uncertainty been acknowledged where it exists?
A well-documented file is not defensive. It is disciplined. It protects the practitioner and the client.
Ethics as Structural Tension
Ethics in tax practice is not abstract compliance. It is the management of competing pressures.
Clients want certainty.
Businesses need revenue.
Regulators expect diligence.
Practitioners must exercise independent judgment.
Circular 230 sits in the middle of these forces. It does not eliminate pressure. It provides the framework for navigating it.
The real ethical test is not whether we understand the rules. It is whether we uphold them when the client becomes the pressure.
And in those moments, professionalism is not loud. It is steady.
 Juan Ojeda Jr. is a tax professional with experience advising closely held businesses on entity structuring, compliance, and planning. He is an academic associate member of the National Association of Enrolled Agents and is currently pursuing the enrolled agent credential.
Related Content